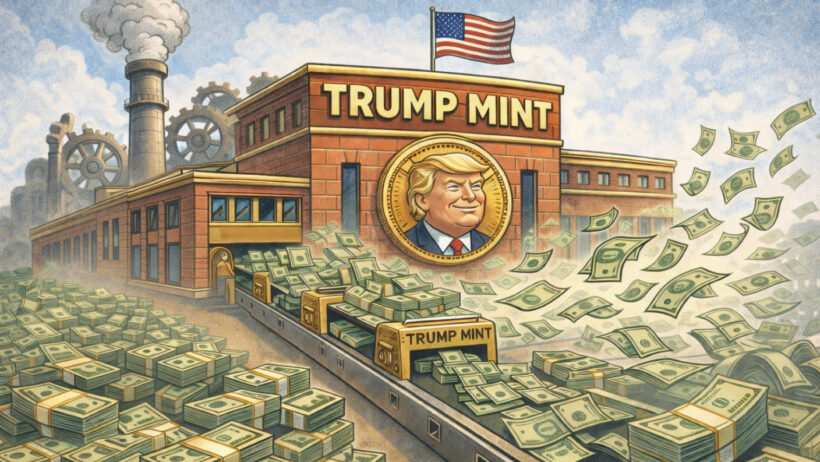
Eastern philosophy often echoes the wisdom of Sun Tzu to “leave your adversary a dignified path for retreat.” That, however, is not Donald Trump’s mantra when it comes to doing deals and making money. Trump does not leave much on the table after a negotiation—a fact which he is very proud of. He is more likely to have sold the other side’s furniture in the process.
For Trump, business—as in most things in life—is a zero-sum game. And for Trump, it’s all about making sure that he is the winner.
There is a certain logic—ruthless, but consistent—to how Trump structures deals. He rarely takes on the riskiest portions himself. He prefers to offload downside risk whenever possible while retaining the upside. It is what might be called the art of stealing the deal: heads I win, tails you lose.
Trump’s first major Manhattan transaction, the Commodore Hotel, set the pattern.
The property, adjacent to Grand Central Station, was owned by the bankrupt Penn Central Railroad and desperately needed a rescuer with political connections. Donald Trump, then only thirty years old, lacked the capital and reputation to independently finance such a project. But he possessed one crucial advantage: his father, Fred Trump, had longstanding ties to New York Mayor Abe Beame.
Leveraging those connections, Trump secured extraordinary concessions. Rather than purchasing the hotel outright, the state’s Urban Development Corporation bought the property and gave Trump a ninety-nine-year lease. He negotiated a forty-year property tax exemption—the first ever granted to a commercial property in New York City. That exemption alone made the economics viable.
The structure effectively de-risked the project for Trump. If it succeeded, he captured the upside. If it failed, the public would shoulder much of the burden. He then enlisted Hyatt as a partner and used his father as guarantor on construction loans. When the Grand Hyatt opened in 1980, it generated millions for Trump annually.
This was merely his first big deal, but the contours of the Trump deal were already clear, with certain timeless patterns emerging clearly.
First, Trump rarely buys anything other than distressed assets, whether in bankruptcy or near bankruptcy, from highly motivated sellers strapped for cash and desperate for relief.
Second, Trump rarely purchases anything at full price or anywhere near top dollar. Buying property from those down on their luck and driving the hardest deal possible became a Trump specialty. Paying top dollar in frothy markets is never Trump’s preferred approach.
Third, Trump always puts down as little money as possible up front. Whenever possible, he likes to buy things with other people’s money. He generally offloads as much downside risk as possible so that his share of the investment carries minimal exposure while retaining maximum upside for himself. Furthermore, he almost always structures deals in such a way that he is relatively unencumbered, enabling him to wash his hands and walk away if things turn south for whatever reason, while someone else is largely caught holding the bag.
Nothing captures this playbook more aptly than Trump’s transformation from overleveraged, swashbuckling real estate developer into a media personality funded primarily by highly favorable, low-risk (for himself at least) branding and licensing deals. Thanks in part to the popularity of The Apprentice reviving his brand at the turn of the century, his name became more valuable than many of his properties. Income increasingly flowed from licensing deals rather than development.
The list of endorsed products became almost comically long: Trump Steaks, Trump Vodka, Trump Ice, Trump Watches, Trump University, Trump Mortgage, Trump sneakers, Trump NFTs, Trump coins, Trump guitars. The model was consistent: collect fees, invest little, retain branding control, and avoid capital risk. If the product failed, the downside was someone else’s problem.
In recent years, critics argue that the monetization has grown more brazen. Crypto ventures, licensing deals, litigation settlements, and international projects have generated billions. Truth Social, despite modest revenues and significant losses, achieved sky-high valuations. Meme coins and digital tokens tied to the Trump brand attracted vast sums, not to mention Mar-a-Lago crypto summits hosted by Trump family businesses.
Critics decry many of these deals as opportunistic excess, but the basic underlying pattern remains timelessly recognizable: maximize upside, minimize personal exposure, monetize brand leverage, and treat every transaction as a scoreboard.
For Trump, money is not merely wealth—it is the ultimate measure of victory. Supporter and critics alike cannot begin to understand Trump, and how to anticipate his actions, without recognizing the primacy of money in his worldview.