This piece originally appeared in FIN, James Ledbetter’s fintech newsletter.
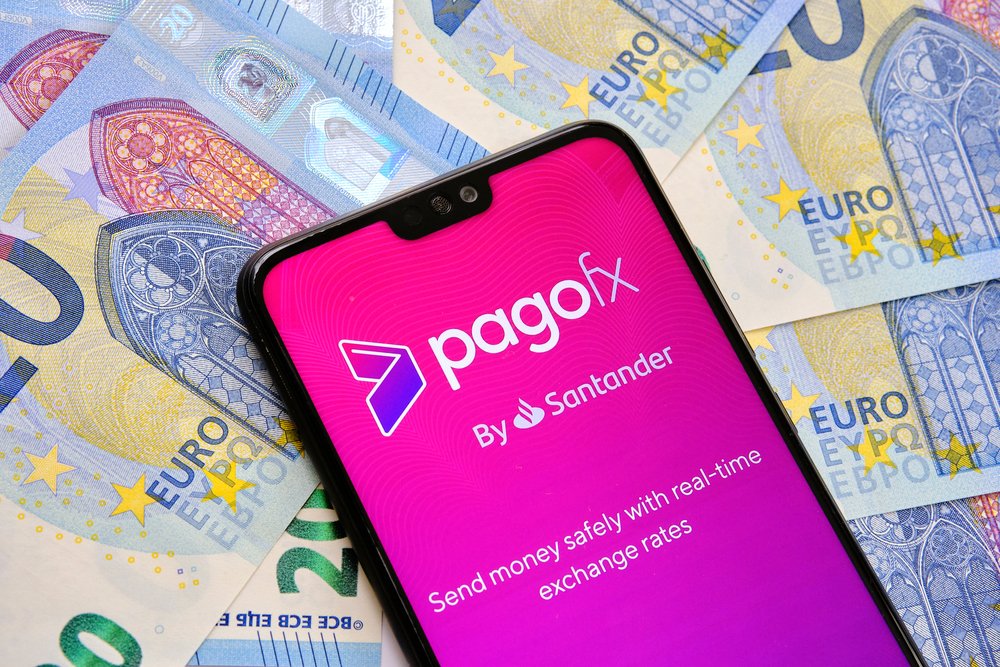
This week witnessed major fintech pullbacks by two of the largest multinational companies in the world. The Spanish banking giant Banco Santander is shutting down PagoFX, the cross-border money transfer service it announced last April to considerable fanfare. The service allowed consumers in the UK, Spain and Belgium to transfer money overseas and was intended to compete with Wise and Revolut. Santander, which is the 16th largest bank in the world, said it is closing the service following a “strategic review.”
Then on Friday, the Wall Street Journal revealed that Google is pulling back on its wildly ambitious plan to expand Google Pay into Plex, which was supposed to offer a wide variety of banking and payment services around the globe.
The short digital lives of these fintech megaprojects provide an object lesson in why it is so hard for big multinational institutions to truly innovate. (The corporate backtracking trend also casts doubt on Visa’s announcement this week for a global network of interchangeable central bank digital currencies, with Visa at its center.) The problem is not a technology deficit; if Google can’t figure out how to be a market-leading digital payments company, then no one can. It’s not usually a regulatory problem, although it’s probably true that huge, public companies will be more sensitive to acquiring new regulator concerns than scrappy startups are.
No, the culprit is usually misaligned incentives: if you’re trying to create something new and disruptive within a big company, there is a decent chance you’re threatening some existing revenue source. In Santander’s case, the conflict appears fairly explicit. Back in 2017, the Guardian published a leaked memo from Santander showing that nearly a tenth of Santander’s 6.2-billion-euro profit in 2016 came from money transfers, and that the bank was charging six times as much as the company then called TransferWise was charging for a transfer of 10,000 pounds. PagoFX’s competitive transfer rates were designed to close that gap, but perhaps the “strategic review” determined that Santander doesn’t really want to close it.
In Google’s case, the pullback of Plex is less obviously about threatening existing revenue, and more about the type of business that Google ultimately wants to be.
A Google spokesperson gave the standard statement to FIN:
We’re updating our approach to focus primarily on delivering digital enablement for banks and other financial services providers rather than us serving as the provider of these services. We strongly believe that this is the best way for Google to help consumers gain better access to financial services and to help the financial services ecosystem connect more deeply with their customers in a digital environment.
Digging a little deeper into this enabler vs. provider dynamic, the WSJ story says:
Bill Ready, a former PayPal Holdings Inc. executive who joined Google a little over a year earlier to head up its e-commerce operations, took over and set a new course, people familiar with the matter said. Mr. Ready was concerned that Plex could make other banks think that Google was out to compete with them since it played a lead role in building the product, one of the people said.
The notion of bank competition is real enough; as some stock analysts noted Friday, Google has a lot at stake in offering cloud services to banks, and must expect that business to grow. (The Plex news, which broke when the market was open on Friday, had no obvious impact on Alphabet stock.) Still, it is kind of a weird explanation that makes Google look slow-witted—We didn’t understand that by offering bank accounts and issuing credit cards we might be perceived as…competing with banks…oh wait—and it may not represent the entire truth. Yet within the meandering logic that often guides corporate strategy, it sort of makes sense: a giant company chases the fintech bandwagon only to realize that, if they do it in a bold way at significant scale, it eventually and awkwardly redefines the company in a way that conflicts with its core identity. In this sense, it will be a miracle to see the Facebook-driven stablecoin Diem actually come to life, although Facebook’s exhaustive assertions that “It’s not us, it’s the Diem Association” might be a way of squaring that circle.
Google will still be intimately involved with money transfers, of course; Google Pay claims 150 million customers in 30 countries use the service, although the revenue it generates is dwarfed by Google’s advertising revenue. The whole point of Plex was to build up that part of Google’s business, but it’s not as if the failure to do so threatens the company as a whole.
Santander, however, has no such excuse. It’s a bank, and if it can’t find a way to compete against the fintech upstarts, eventually it’s going to see those lucrative transfer fees dry up.
Crackin’ Down on Kraken
The US regulatory lightning bolts are coming down fast and often these days, not completely illuminating the full oversight philosophy but certainly providing ample evidence that the Biden Administration insists that fintech and crypto companies play by the rules. With almost every enforcement action, the inadequacies of the regulatory system and the effects of years of unintelligent neglect are on display, but the intent is clear and even the industry’s biggest players will not get a pass.
This week, the Commodity Futures Trading Commission (CFTC), an agency not often considered at the forefront of fintech regulation, slapped a $1.25 million fine on Kraken, one of the oldest cryptocurrency exchanges in the country (and world). Kraken’s sin was offering “margined retail commodity transactions,” which the CFTC has clearly said can only take place on a designated contract market. In several of its details, this action shows what’s right and what’s missing in so much of crypto regulation.
This was not Kraken’s first brush with regulators. Back in 2018, Kraken declined to cooperate with a New York State inquiry into virtual markets. Kraken CEO Jesse Powell said at the time that his company had pulled out of New York when the state imposed its BitLicense requirements, and since it wasn’t doing business in New York it could ignore the Attorney General’s request for information. Powell infamously compared New York to being stalked by an “abusive, controlling ex.” The state, for its part, called Kraken’s failure to cooperate “alarming.”
This time the tone was much more conciliatory. Kraken sent FIN a statement that reads in part: “We appreciate that the settlement acknowledges our cooperation and engagement on the issue. We are committed to working with regulators to try to ensure the rules governing digital assets create a level playing field globally — one that allows the crypto space in the U.S. to flourish, while protecting the interests of individuals and the integrity of the industry.”
Kraken, while clearly in violation of the law, could be forgiven for feeling a little persecuted here. As CFTC Commissioner Dawn Stump pointed out in a concurring opinion, the application of the law in this fairly arcane area is not exactly transparent. With its focus on a single aspect of Kraken’s business, the CFTC resembles the recent SEC action against Coinbase; the cops catch you on a parking ticket to demonstrate that they’re coming after your mansion.
But at the same time, it’s hard not to see Kraken’s actions as self-inflicted wounds. You’re in business for ten years, you are offering what any competent compliance lawyer should tell you is a futures contract…so why not register with the appropriate agency? Wouldn’t that make things easier for everyone?
This piece originally appeared in FIN, James Ledbetter’s fintech newsletter. Ledbetter is Chief Content Officer of Clarim Media, which owns Techonomy.