This piece originally appeared in FIN, James Ledbetter’s fintech newsletter.
It seems abundantly clear that stricter US regulation of stablecoins is imminent. Federal Reserve chair Jerome Powell recently testified before House and Senate committees, and there were moments when he seemed almost vexed by stablecoins. Powell told a House committee:
We have a tradition in this country where the public’s money is held in what is supposed to be a very safe asset. That doesn’t exist for stablecoins, and if they’re going to be a significant part of the payments universe…then we need an appropriate framework, which frankly we don’t have.
At another point, asked about the possibility of a digital currency issued by the Fed itself, Powell was a little more emphatic:
You wouldn’t need stablecoins; you wouldn’t need cryptocurrencies, if you had a digital U.S. currency. I think that’s one of the stronger arguments in its favor.
We should learn a lot more in September when the Fed is scheduled to issue a white paper on digital currencies.
Still, Powell’s testy testimony did not come as a surprise. It was at least the third signal in recent months hinting that Fed officials are somewhere between concerned and alarmed about the hyperbolic growth of stablecoins. A bit of background: US financial regulators closely watch the volume and volatility of prime money market mutual funds. The chances are good that if you have an investment account with, say, Schwab, your “cash” assets are parked in such funds, which earn a micro-level of interest but, most important, don’t generally lose value.
This multitrillion-dollar stack of money is considered especially important because it is highly liquid and usually stable (although before and during recessions it tends to jump around a bit). Money market funds aim to maintain a net asset value of $1 a share; on the rare occasions when these funds “break the buck” it causes a lot of anxiety in the financial system.
So: in a speech and interview in late June, Boston Federal Reserve president Eric Rosengren pointed out that some stablecoins—he specifically named Tether, which we’ll explore shortly—look and behave a lot like these money market mutual funds, a point that Powell echoed this week. The chief difference is that the mutual funds are issued by institutions that are regulated, while stablecoins are not. It’s perfectly logical to think that a stablecoin designed to be 1:1-pegged to the US dollar would provide a viable alternative to money-market funds; both assets appear to be liquid and relatively stable. What’s a little less logical is that stablecoin ownership would start exploding in a short period of time. Below is an eye-popping chart that Rosengren used in his June presentation:
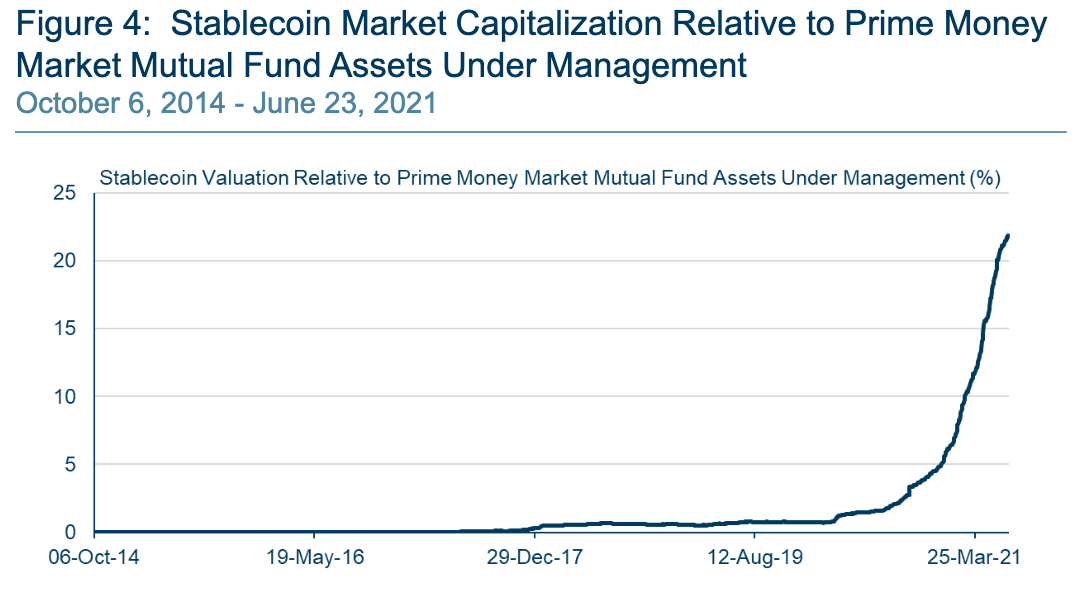
In just a few months, the value of money stored in stablecoins skyrocketed from about 2% of prime money market assets under management to more than 20%. That kind of neck-snapping growth is highly unusual in this sleepy-by-design area of finance. It worries regulators because it concentrates a lot of market power in an asset that’s largely opaque: Who owns all that stablecoin? Who manages it? Why has it taken off so dramatically? How sturdy is the financial and technological infrastructure holding it up?
There are few reliable answers to these vital questions, because stablecoin is all but unregulated. From a market description perspective, it’s worth mentioning that one of the primary use cases for USD-pegged stablecoins is to provide a digital holding station for individuals or institutions who want to move from one cryptocurrency to another without going through any dreaded fiat currency. In this sense, the growth in stablecoin adoption is a side effect of the increased interest in cryptocurrency, so its rise makes directional sense (even so, that’s a steep curve).
But if you are Jerome Powell, that’s not your main concern. Your main concern is: What would happen if a big chunk of those stablecoins were to change hands all at once—or to disappear? Would a market disruption that’s now more than 1/5th the size of the stability horse you’ve bet on spook your horse as well?
The concern is especially intense because there is substantial reason to think that the stablecoin market is nowhere near as clean as it should be. The largest USD-pegged stablecoin is Tether; recent estimates indicate that Tether has a market capitalization of $60 billion. In theory and in promise, all Tether coins are backed with reserve assets consisting of “traditional currencies” equivalent on a 1:1 basis to US dollars. In practice, it’s an established fact that this has not always been the case. In February, New York Attorney General Letitia James reached a fraud-investigation settlement with Tether and the crypto trading platform Bitfinex, fining the companies $18.5 million and banning them from conducting business in the state. In the agreement, the attorney general noted that Tether lost its banking relationship with Wells Fargo in March 2017. For several months following, Tether was incapable of holding reserve assets to back up the approximately 442 million Tether coins that were then in circulation; it had only about $61 million in a Canadian bank account. Tether and Bitfinex then got in bed with a Panamanian shadow bank that was indicted for fraud in 2019 in the Southern District of New York.
If Tether had trouble backing up its coins when there were only 442 million in circulation, it is understandable for the Federal Reserve to wonder how the company is handling the recent surge. (And given the way that Tether props up the Bitcoin market, holders of Bitcoin should be equally troubled.)
Of course, the big question is: if the US government is going to regulate stablecoin, what will be the legal mechanism? One of the general challenges with the fintech revolution has been that it’s like a weed that grows up through the various cracks in the regulatory sidewalk. Should, for example, stablecoin be treated as an asset that can only be issued by a chartered bank? Are there grounds for regulating stablecoin as a security, like a stock? FIN will explore this issue in Part II next week.
Why the UK Dominates Open Banking
One of the most powerful financial developments in recent years has been the development of open financial data, also known as “open banking.” Banks hold a tremendous amount of information about our financial lives, so voluminous that not even the most sophisticated bank could fully take advantage of even a fraction of it. Open banking is an agreement among major banks to share certain anonymized financial data with outside parties, who can then use that data to build applications for new consumer products and services.
In the UK and Europe, open banking applications have grown in response to legislation. In the US, open banking is in the hands of the private sector, with some banks and data providers (such as Fiserv) moving ahead while others have yet to take any action. This week, McKinsey issued a detailed article about the state of open banking. FIN was struck by just how far ahead the UK is, with its lead gaining over time:
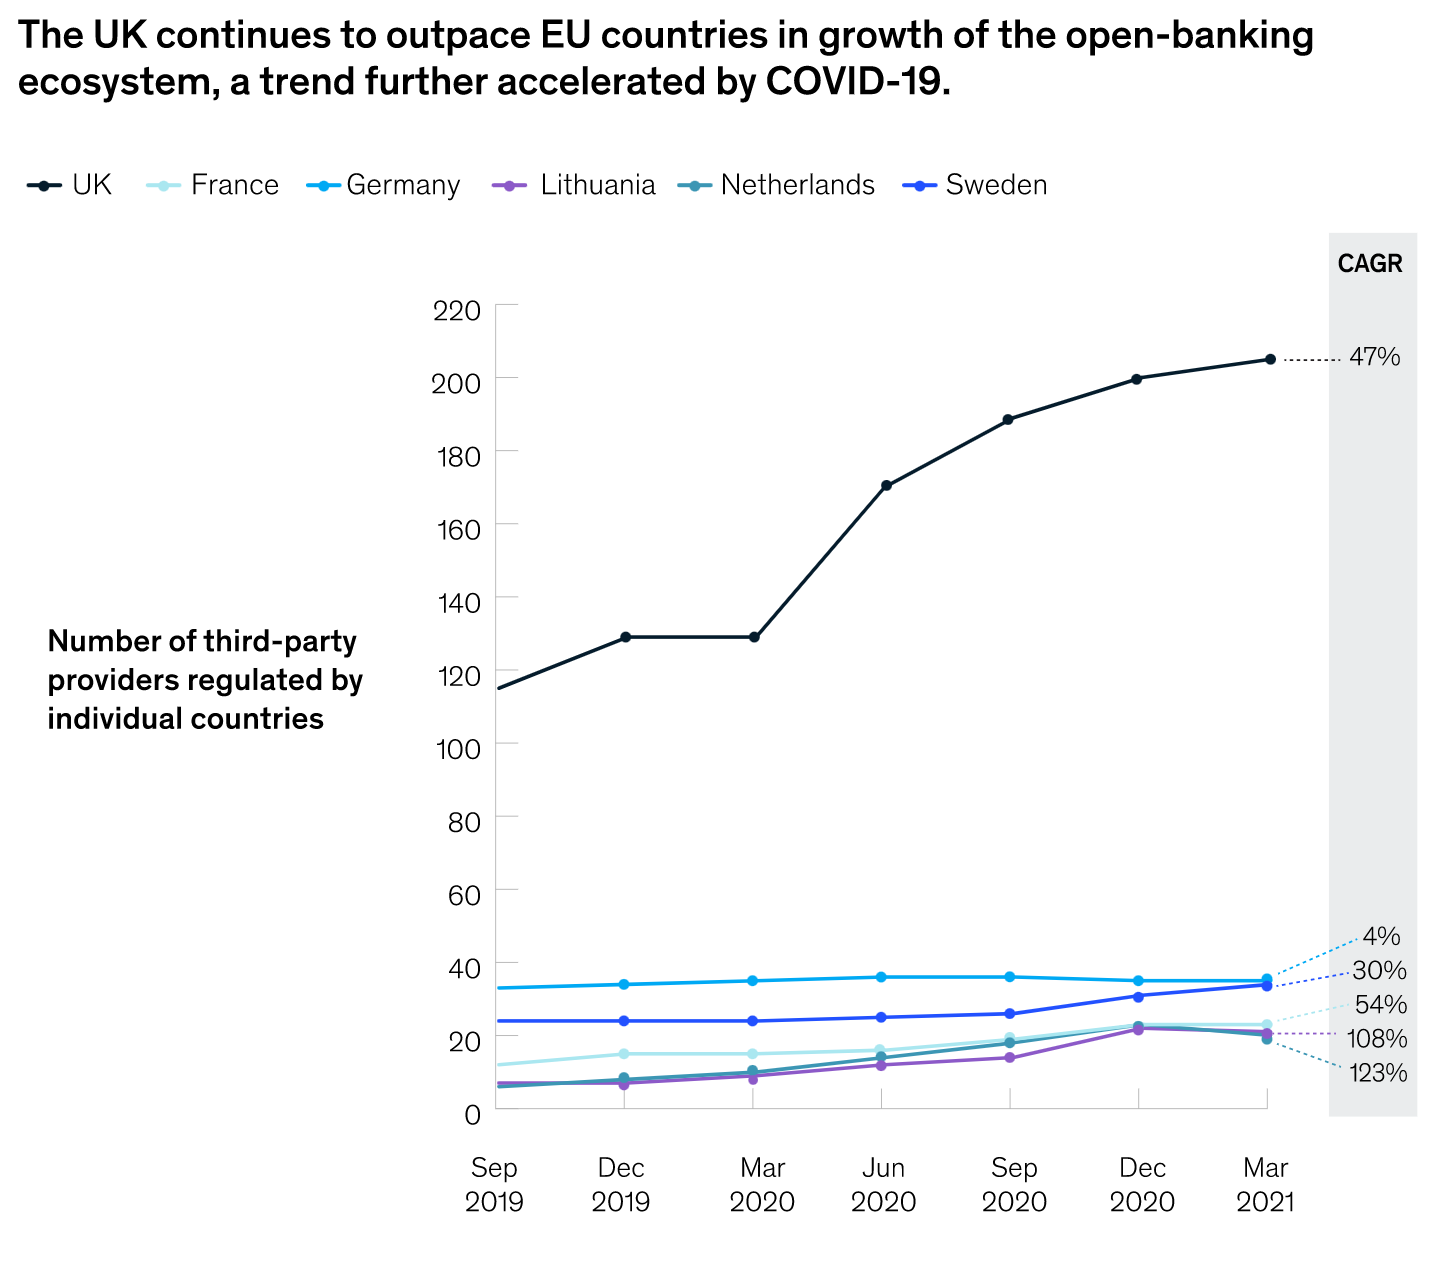
Why is the UK so far ahead, even of countries like Germany and France which have roughly comparable populations? In an exclusive FIN interview, McKinsey senior partner Tunde Olanrewaju explained that the continental European countries interpreted the EU legislation known as PSD2 in a narrow way, focusing only on bank data pertaining to payments. In the UK, the financial sector created a far more expansive definition of the type of data it would make available. Offering an example, he said: “Somebody can now pull from my accounts all of the money I spend and tell me ‘Here are the 50 subscriptions you have. Would you like to do something about it’?” This embrace of open banking is a big reason why the British fintech industry is as robust as it is.
This piece originally appeared in FIN, James Ledbetter’s fintech newsletter. Ledbetter is Chief Content Officer of Clarim Media, which owns Techonomy.