Early this year, six of the country’s largest banks reported earnings for the fourth quarter of 2014. Five of them—Bank of America, Citibank, Goldman Sachs, JPMorgan Chase and Morgan Stanley—either missed analyst expectations or reported a drop in earnings. Three were hit by almost $6 billion in legal fees incurred the preceding quarter.
Though it doesn’t attract nearly as much attention as the other five, the sixth bank, Wells Fargo, reported earnings growth and met analyst expectations. With a stock price in the low 50s, Wells Fargo is now the most valuable bank in the world by market capitalization.
For Wells Fargo CEO John Stumpf, the results were further vindication of his bank’s meat-and-potatoes, retail banking strategy: to perform a bank’s core operations—checking accounts, mortgages and loans as well as investment advice—and emphasize client service so as to foster long-term relations with customers. Wells Fargo operates “in the real economy,” Stumpf says pointedly. “We don’t know about cornering the aluminum market.”
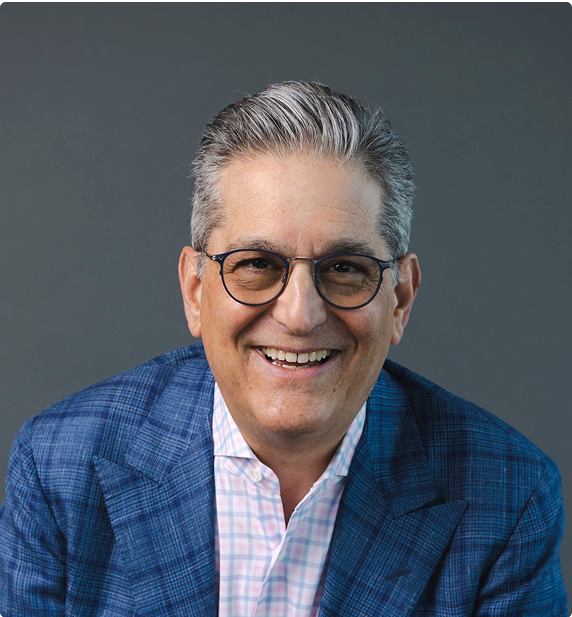
Stumpf, 61, so passionately articulates Main Street values that he can remind you of Jimmy Stewart. The parallel doesn’t completely work—Stumpf was the country’s highest-paid banker in 2012, with compensation of almost $23 million—but there’s no question that he came by his beliefs during a simpler time. Born in 1953, Stumpf grew up in Pierz, Minn., population about 1,000. His parents, Herb and Elvira, owned a small dairy and poultry farm. One of 11 children, Stumpf shared a bed with two of his brothers until leaving for St. Cloud State University, also in Minnesota. His career in banking began after graduation when he got a job as a repo man at First Bank in St. Paul, Minn.
Stumpf would move on to more traditional banking jobs for Northwestern National Bank, later known as Norwest, steadily moving up the corporate ladder. After Norwest merged with Wells Fargo in 1998, Stumpf would become Wells Fargo president in 2005, CEO in 2007 and chairman in 2010. It was a time when most bank heads weren’t exactly relishing their jobs, but Wells Fargo emerged from the financial crisis not only intact, but virtually unscathed—a bank whose nothing-flashy ethos was perfectly suited to a post-crisis world.
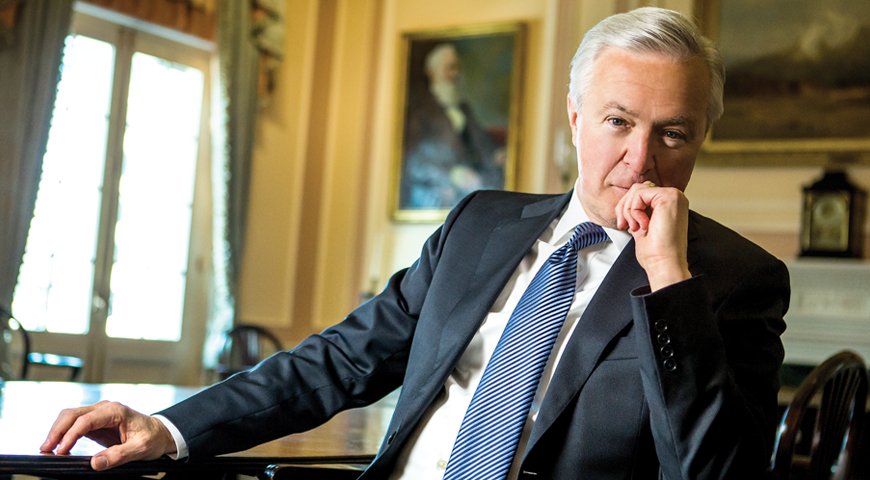
I met with Stumpf in his office on the 12th floor of Wells Fargo’s headquarters on Montgomery Street in San Francisco. It’s a big office but not a lavish one—the furniture has seen better days—and by design it lacks a door.
On the surface, the CEO is easygoing, relaxed, almost grandfatherly. “The measure in life is wisdom,” he says. “I know a lot of smart people who aren’t very wise, and I know a lot of experienced people who aren’t very wise.” He was talking about how he did in high school—not well—but it was hard not to wonder if he wasn’t referring to his own profession.
Q: In terms of stock valuation, Wells Fargo is now the most valuable bank in the country. What does that mean to you, and how did you get there?
That valuation is not the reason for what we do. The reason for what we do is that, one way or another, we serve 70 million families. And we largely are an American company—97 percent of our assets are in the U.S.—which makes us largely different than any other big banks in the U.S. Way different than Citi and Chase.
Not like the New York-based investment banks, in other words?
The best description of us, if you think of West versus East—it is probably most accurate to say “real economy” versus “not the real economy.” We have more small-business customers than anyone else, we make more profit than anyone else, we make more mortgage loans, we do more ag loans, we make more commercial real estate loans. So as the economy does well, and as our customers do well, we do well with them.
Is the market cap important? Absolutely. But we don’t say, “We have to make more money than anyone else, we have to make a larger market cap than anyone else.” That doesn’t even enter our thinking.
Once you’re at number one, does that create pressure to stay there?
I don’t think so. What pressure I feel and our team feels every day is, are our ATMs up and working? Is our online the best in the industry? Is our cross-sell where it should be? Are we helping customers financially?
These are the things that drive us. The companies that got in trouble [during the financial crisis] put the stagecoach in front of the horses—they put profits first.
Let’s talk about the financial crisis, which Wells Fargo weathered without any major financial shock or legal consequence. In the past, you’ve told a story from 2003 in which you and several colleagues discuss a competitor—Countrywide Financial—that wanted to become number one in mortgage lending, a ranking Wells Fargo held at the time. You and your colleagues looked at the measures Countrywide was taking to reach that position, and decided you would not do the same. Can you tell me a little more about that decision?
It happened around this table we’re sitting at now. Remember that we have 10,000 team members who are home mortgage loan consultants. They’re in the marketplace, and some of them were saying, “This other company wants to be number one and they’re going to do negative amortization, meaning that clients can borrow money [against their mortgages] and owe more on their house than they started out with.”
And the question was, why can’t we do this? Can we defend our position?
And we said, “Well, that’s inconsistent with our values.” We really want to help our customers financially. Can giving a mortgage to someone where they owe more than they start out with make sense?
So the decision was to stand pat?
And we lost team members for that, because they said, “I can go do that over there and make more money.” If we do a good job, we will get rewarded. But our job is not to harvest our customers and put them up to benefit someone else.
Was it a hard decision?
It was hard because we had team members who were going to be impacted. We gave up billions in originations, hundreds of millions of dollars of profits in that time. But it was not hard from the perspective that, if you do what’s right for your customers…
There were a lot of people during that time who would originate a loan, package it and sell it. We call that the moving business. We’re in the storage business. We make our loans; we keep them.
Has that kind of risk-taking gone away?
There’s a lot less today than in the run-up to 2008, but those things are playing out in smaller ways. There are leverage loans being done, deeply subprime auto loans. There are corporate prospects where, if you finance their loan, they will let you do some of their investment banking services.
So some banks are slipping back?
There’s more discipline today. Where a lot of things are happening, though, is outside the regular [banking] industry. As the industry builds capital, builds liquidity, has mountains of regulations, things are happening on the outside. You’ll find originators for credit cards, payday lending, auto loans—they’ll take a lot of risk, but they’re not in a bank that’s regulated.
Wall Street really never did a fundamental assessment of the role corporate culture played in excessive risk-taking. Culture is something you talk about a great deal…
I’m the keeper of the culture—not alone, but my job is to represent and communicate the culture.
Norwest, where you started working in 1982 and which merged with Wells in 2008, also had a client-centric, team-oriented culture. So when you say that you’re the keeper of the Wells Fargo culture, what part is Norwest, what part is Wells Fargo and what part is John Stumpf?
I’ve worked for three Wells Fargos in my life. The first was called Norwest. Norwest was a Minneapolis-based holding company started in ’29, and then, as Norwest and Wells Fargo came together, we went from an upper Midwest regional to a much bigger company. Legally, Norwest bought Wells, but it was treated as a merger of equals. That was June 8, 1998. Then six years ago, I started working for the third Wells Fargo when [Wells Fargo acquired] Wachovia.
Mr. Stumpf Stakes His Claim

So the culture is a combination of all those. We specialize in plural pronouns more than possessive pronouns: “us, we and ours” is dominant here versus “I, me and my.” We play “us” ball.
As I’ve walked around your headquarters, I’ve noticed a certain frugality. The décor is a little dated, the furniture almost run-down. Is that deliberate?
That is deliberate. When you’re involved in a real economy, you want to be able to identify with people. This chair [Stumpf points at a chair next to the one on which he is seated and pulls some stuffing out of its torn seat] is legendary in the company. I ride the elevator with everyone else. The star of this team is the team. It’s surely not me.
How do you find that quality in your potential employees—their ability to thrive in a team-oriented environment?
One of our legacy values and sayings is that we don’t care much until we know that you care. We can’t teach “care.” Caring is part of one’s innate makeup. We try to hire people who care and then we’ll teach them what they need to know, as opposed to the other way around.
Is Wall Street culture healthy?
I don’t know. And I’m not being clever; I don’t know it that well. I’ve only been on Wall Street a few times—we don’t have offices there. I don’t even know what Wall Street culture means, to be honest with you.
Let me rephrase. The banking-related headlines of the last few years—JPMorgan, Goldman Sachs, Citi—have focused on investigations, scandals, billions of dollars in fines. Do you ever think to yourself, what’s going on over there?
Our DNA is much more community bank-like than it is money-centered bank-like. We have much more in common with PNC or U.S. Bank or SunTrust than we do with money-centered banks. Not that we don’t serve large clients—we surely do. But we don’t have large trading platforms, we don’t have big derivative desks, we don’t know about cornering the aluminum market—that’s not who we are.
And the other thing is, most of our team members are involved in businesses where they’re paid a salary plus something else, as opposed to having it all commission-based. And that matters. We try to make the dominant culture more of a family kind of thing.
So compensation is structured in a way that reinforces the culture.
Absolutely. We would never let compensation drive culture. Our customers aren’t our counter parties, they’re our guests.
You won’t find in the San Francisco Chronicle, as you do in the New York Times, an annual story about expectations for year-end bonuses?
If there was a story about it, that’d be inaccurate. And another cultural thing is, also, we like each other. Somehow people think you have to be adversarial to get high performance [out of employees]. We think it’s just the opposite. The 11 people who directly report to me average about 28 years with us. I know them, I know their kids and I know their grandkids.
On the subject of family, let’s talk a little bit about yours. You joke sometimes about growing up on a farm, one of 11 children with one bathroom and shared beds. On the one hand, it sounds like the Waltons. But it must have had its challenges.
It’s not as romantic as it sounds. It’s cold in Minnesota—I laugh at it now, but [my siblings and my] birthdays are all from July 13th to October 28th, so you do the math. My father is fifth-generation American, but his first language was German. And my mother is a registered nurse. They’re just fabulous people. But we were very poor. We had a 120-acre farm…
That’s a small farm.
It’s a small farm. My dad would say that on the farm, he didn’t raise crops or cows or chickens or pigs, he raised kids. That was his priority, and the same with my mother. But I didn’t particularly like the farm. I smelled like a Holstein until I was 18. I get up at 4:30 in the morning even now because that’s what it was on the farm. It just stays with you.
Were you more of a student than a farmer?
I wasn’t a good student in high school. It wasn’t a particularly good school. I didn’t care about that. What my parents gave me is the value of hard work, how to play a team sport, how to get up off the mat when you’ve been knocked down.
For example?
I knew how much trouble we were in financially by the time I was 6 years old.
How much trouble were you in?
We bounced between bankruptcy and foreclosure until I was probably 15 or 16, when we got a chicken farm, where we had 15,000 laying hens. And then all of a sudden we had regular income.
When did you first realize the severity of your family’s financial situation?
I knew when a banker came to our farm and we couldn’t make payments. I knew when the power and light company kept turning off the lights.
That must’ve been scary.
It has an impact. And it wasn’t that my parents were doing anything wrong, it was just that there were a lot of mouths to feed, and a small farm, and poor land and poor crops. It was tough.
Did that poverty affect things like the clothes you wore and food you ate?
It affects everything. It affects everything.
How did the family handle it?
There was never a sense of despair, never a sense of “why us?” or “why do the neighbors have more?” We dealt with it as a team. So it was…tolerable. I mean, I wouldn’t want to live it again, but I wouldn’t trade it for anything. Positives came from that.
You had bad grades in high school, and you played bass in a band, the Mason-Dixon Line. Were you rebellious?
No. None of us, none of the 11 children, were ever rebellious. Because of our parents—none of us would ever do anything to embarrass or hurt or in any way destabilize our already challenging situation.
When did you decide to be a banker?
Well, I met my wife in third grade—and she’s still my first wife, we’ll have our 40th anniversary in May—and her dad worked at the bank in my hometown. Some people would suggest that that was the connection, but it really wasn’t. Banking just appealed to me. I was buying and selling eight-track tape recorders—you know, for your car—and I was buying and selling cars to make a little money, and I liked everything that happened at the bank. It was the center of commerce, and that appealed to me.
In a small town like Pierz, the bank must be a unifying force.
It is! There’s only one bank in that town. If it closed down, that town would blow away.
You left home to go to St. Cloud State University.
I did, and I loved every minute of it. The idea of competing—it quickly became, “I don’t want to get a good grade, I want to beat everyone else.” Then I graduated in the spring of ’76—there were no jobs to be had.
What did you do?
So, the only job I can get is as a repo man [laughs]. At First Bank. I would’ve killed to be a teller.
What was repossessing cars like?
I’m in the [bank] basement. And Mondays I’m Richard York, Tuesdays I’m Joe Blow—you couldn’t even use your own name! Too dangerous.
What did you actually do every day?
You get to work at about 10 in the morning, and you would “beat the sheet.” Those were the days of the big IBM printers, and whatever happened the day before would come out on a big green sheet, and you’d start calling the names [of creditors] on it and getting promises. And then, after working the sheet, you’d go home, take a quick nap, eat dinner and go out and repo at night.
Aren’t repo guys pretty tough characters?
Oh, no. You just gotta work hard and not be very smart. But it is a fabulous place to learn about making loans because you can see very quickly that loans don’t just happen to go bad. Most of them are bad when they’re made.
So you learned when not to make a loan?
Exactly. It wasn’t good for the customer, wasn’t good for the bank, wasn’t good for the shareholder.
Did you like the job?
Kids today think that computers are exciting, but let me tell you something…. First of all, you know what you’re looking for. You know the color, make, model and find it at a liquor store at 12:30 at night and—this is before cellphones—you go as fast as you can down to the 7-Eleven, you call a tow truck. The tow truck comes, starts to lift this car off the ground and some guy walks out of a bar. He’s about 6 foot 6, he’s got two six packs of confidence in him and he wants to know what you’re doing with his car. Now, that’s exciting.
There must also have been times where you were taking a car from someone whose livelihood depended upon it.
No question. And I never thought of these people as deadbeats. I never thought of them as something less than me. These are people who came across something difficult in their life. When you have to go to repo is when they’re hiding from you and they don’t ever intend to make a payment. But I would bend over backwards to make something work.
The type of banker that you were becoming is very different than the modern perception of a banker.
That’s probably true. I’ve been in this industry for 40 years. I’ve done virtually every job. So when people talk about, how do cash letters work, or payments, or whatever—I know this stuff. I wasn’t from an investment bank; I grew up in the industry.

You used to walk to work at about 5 a.m. Since the Occupy Wall Street demonstrations, when your colleagues grew concerned about your safety, you take a car.
The skunks and the squirrels were gonna get me, or something like that.
How did you feel about that?
Everyone in America felt poorer after 2008—we lost jobs, we lost homes. And the narrative was that the financial services industry caused this—this was avoidable but for the greed of the industry.
So it’s understandable that people would be angry. And even though the facts might be different, when you have facts up against emotion, emotion always wins the argument. I never felt sorry for us or the industry. I felt sorry for the people who lost homes.
In 2009 Wells Fargo cancelled an employee excursion to Las Vegas because of public perception that a bank that had taken TARP money was spending it on a Vegas junket. You took out ads in the New York Times and Washington Post defending the trip. Why?
Every year here until that time, our top performers [would be given a trip]. It wasn’t only people in sales. It would be tellers, people at the service desk, customer service reps. And these weren’t $50,000 trips; they were a couple thousand dollars. And the funds didn’t come out of the taxpayers’ money. We had made $5.5 billion in profit for the first three quarters of that year—we didn’t need their money. But we were told [by the government] that [TARP money] wasn’t an offer, it was an order. So I took out this ad and said, “Here’s the rest of the story.”
Those ads were widely criticized. New York Times columnist Maureen Dowd called them “inadvertently hilarious.”
You get pretty thick skin after a while. She’s entitled to her opinion.
This brings me back to the question of leadership. Post-financial crisis, we haven’t really seen bank heads on the East Coast regain the status of authority and credibility that they had pre-crisis, when people treated executives like Lloyd Blankfein and Jamie Dimon like prophets. Does this industry need bank heads in these statesman roles, and are you interested in being such a figure?
Our industry, like any industry, needs strong leadership. But it would be countercultural for this company to have a so-called prophet being treated any differently than any of the other team members. So that’s a foreign concept to me.
But there is a leadership vacuum right now, isn’t there?
There’s no question that our industry continues to work to regain the trust of the American public. We tend to be painted with the same brush.
So how do you regain that trust?
One customer at a time.