This piece originally appeared in FIN, James Ledbetter’s fintech newsletter.
The very first issue of FIN, October 18, 2020, featured an item about the imminent IPO of the insurtech star Root. The excitement around insurtech companies had been ratcheting up since Lemonade’s July IPO. FIN noted that Root
has certainly attracted a lot of venture capital and all the big underwriters. Pre-IPO chatter says that Root will be valued at around $6 billion, much bigger than Lemonade’s public debut.
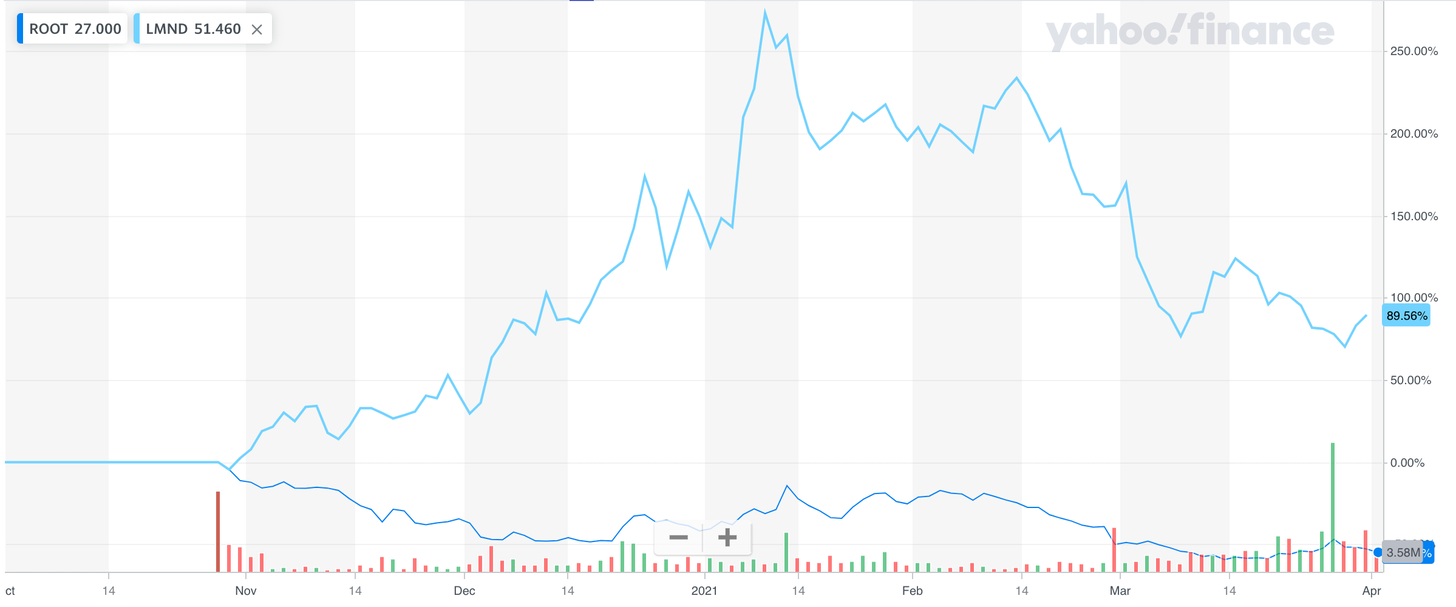
The $6 billion market cap figure was roughly accurate when the stock debuted on October 28 at $27 a share. Since then, amidst an otherwise febrile fintech market, Root has gone underground; as of market close on April 1 its market cap is $3 billion. Root’s lagging performance could be random, but FIN’s October observation about spending remains equally plausible:
While Root’s growth is impressive—150% increase in auto policies from 2018 to 2019—it has also lost a staggering amount of money: some $600 million since 2018, which is more than the total amount the company raised from venture firms.
A big part of the problem, as could be located in Root S-1 filing: “The principal driver of our losses to date is our loss ratios associated with accidents by our customers,” it said. “Establishing adequate premium rates is necessary, together with investment income, if any, to generate sufficient revenue to offset losses, loss adjustments expenses…and other costs. If we do not accurately assess the risks that we underwrite, the premiums that we charge may not be adequate to cover our losses and expenses, which would adversely affect our results of operations and our profitability.”
Thus, FIN concluded in October:
So, arguably, Root’s growth to date is attributable at least as much to undercutting its rivals on price as to its cool tech tools. Given how competitive and capital-intensive the insurance business is, it’s hard to see how a tide of IPO cash alone solves that problem; if Root raises prices, it will lose customers.
While FIN was an early, pre-IPO skeptic, others joined in as the company underperformed. In December, when Root announced its 2020 Q3 results were -$2.20 a share, the company spun it positively, even though it missed consensus estimates and the stock continued to trade below the IPO level. On March 9, Bank of America Securities analyst Joshua Shanker initiated coverage of Root by slapping an “Underperform” rating on the stock. Shanker echoed FIN’s concern about the company’s cash burn, predicting that Root will not be cash-flow-positive until 2027, and thus “will require not insignificant cash infusions from the capital markets to bridge its cash flow needs.” Shanker’s note made an arguably more damning charge: Root pitches its auto-insurance product offering as uniquely based on “telematics,” the ability to gather driving data from customers’ mobile phones, and price their policies accordingly. Shanker pointed out that Progressive and Allstate—much larger companies—have been offering telematics-based products for years.
Perhaps inevitably, a class-action suit was filed against Root in March, alleging that Root’s offering documents made “untrue statements of material facts,” specifically that the company failed to note its weak cash flow and the fact that its competitors use similar technology. Here is a super-important point: these cookie-cutter plaintiff suits against newly public companies are as common as Mark Zuckerberg apologies. Most of them fade away, and most of them should. The suit, alas, has also made everyone skittish. Root wouldn’t consent to an interview, and Bank of America declined to make Shanker available for an interview, or even provide his March 9 note.
So while FIN makes no comment on the legal merits of the case, the business model weaknesses that the case details ought to give investors, and would-be investors, pause. And it’s quite possible that these weaknesses are already priced in; Root’s stock has been a dog its entire six-month life, as this chart comparing it to Lemonade up until the April 1 market close shows:
In one important sense, Root’s public humiliation is healthy. If the stock market met fintech with a sweeping, indiscriminate embrace, that could provide the basis for a dangerous bubble; that the market can sniff out and punish apparent hype is at least a little reassuring. Unless you own Root stock, that is.
FINvestments
🦈 Number of the Week: Proptech firm Compass priced its IPO at “only” $450 millionprior to its April 1 debut, leading some to argue that, on top of Deliveroo’s weak IPO, investors are becoming more discerning about high-growth tech companies.
🦈 Houston-based High Radius, an AI-powered fintech software company, announced a $300 million Series C round this week, bringing its valuation to $3 billion, or three times what it was ostensibly worth in its January 2020 round.
This piece originally appeared in FIN, James Ledbetter’s fintech newsletter. Ledbetter is Chief Content Officer of Clarim Media, which owns Techonomy.