This piece originally appeared in FIN, James Ledbetter’s fintech newsletter.
Consider, for a moment, the US Supreme Court, where the value of dissenting opinion is widely understood and praised. After all, given the shift over time in politics and values, today’s dissenting opinion is sometimes, very crucially, tomorrow’s presiding wisdom.
In a different category, arguably, is the small regulatory agency, appointed by the executive branch and approved by Congress but designed to be independent of any given administration or political party. These agencies include the Federal Communications Commission, the Federal Election Commission, and FIN’s subject today, which is the Securities and Exchange Commission (SEC).
Such agencies were designed to avoid partisan domination; in the case of the SEC, there are five commissioners, no more than three of whom can belong to the same political party. Assuming then, that dissent (both partisan and otherwise) is built into the leadership of such agencies, do they operate best if they try to forge consensus? Or should they, like the Court, encourage open dissent as a public service?
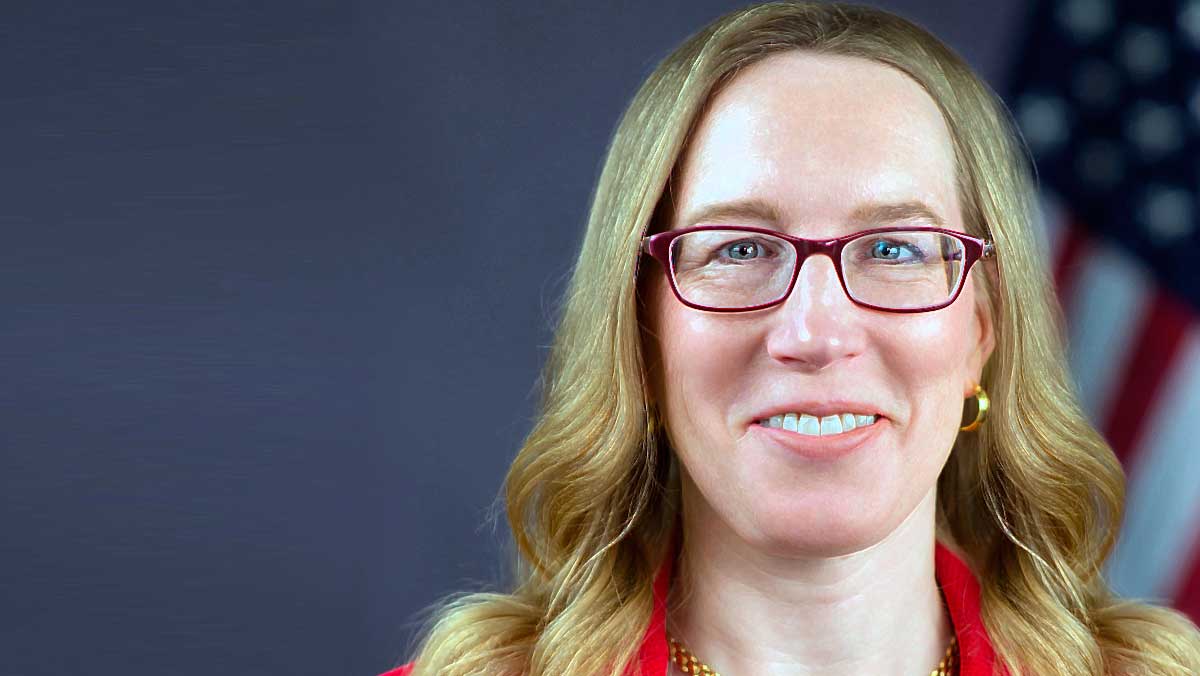
Over the last three years, as the SEC (alongside other federal regulators) has issued fintech and cryptocurrency policies in fits and starts, at least one commissioner—Hester M. Peirce, who joined the commission in January 2018—has been unusually vocal and occasionally witty in expressing her opinion that the SEC has failed to articulate clear and consistent rules for companies to follow. Her advocacy for financial sector innovation has earned her the nickname “Crypto Mom.”

The SEC, both during the Trump years and in the early months of Gary Gensler’s tenure, has issued a handful of decisions that have earned the scorn of many in the fintech and crypto communities. One notable example was denying the Winklevoss-owned Gemini’s request for a Bitcoin-based exchange-traded fund (ETF) in July 2018. Peirce issued a lengthy dissent with 26 footnotes. Not only did Peirce say that the proposal should have been approved, she accused the Commission of “engaging in merit regulation,” that is, the idea that the government prohibits anyone owning a particular security, even if they are willing to take on the risk. She issued a similar dissent when the SEC denied the New York Stock Exchange’s application to allow it to list a Bitcoin-backed ETF. Even when Peirce agrees with a given SEC action, she may well issue a statement indicating her concerns about some aspect of it, as she did this January regarding enforcement against Wireline’s fraud.
Given that she is a Republican hostile to Dodd-Frank and appointed by Trump, it is tempting to pigeonhole Peirce as reflexively pro-finance and anti-regulation. But that’s a mistake. First of all, by design in contemporary America, the SEC is going to have Republican commissioners, and they could be much worse than Peirce. Indeed, Barack Obama first nominated Peirce for the SEC in October 2015, although the nomination was scuttled by Capitol Hill bickering.
And while FIN may have multiple policy and doctrinal disagreements with Peirce, she seems genuinely interested in making the American financial regulatory system work more efficiently and effectively (as opposed to simply wanting to dismantle it). She is a full-on financial nerd; in elementary school her hobby was plotting stock prices.
On individual issues, her views not only have to be reckoned with but are at least partially right. FIN wasn’t around in 2018, but can’t currently see any reason for the SEC to continue to prohibit a Bitcoin- or crypto-based ETF. As we’ve previously noted, Canada and Brazil have already approved Bitcoin-backed ETFs, and billions of dollars have successfully been invested in them. It’s hard to see any remaining technical issues that haven’t been resolved or at least addressed.
The SEC, though, isn’t the Supreme Court, and there’s some reason to think that dissent undermines action. This week, Axios’s Felix Salmon called SEC chief Gensler “the most important financial regulator in the world,” but the Commission is not an autocracy and having Perice constantly bickering in public cannot make his job any easier. Of course, there is little that Biden or Gensler can do with Peirce, given the mandate for Republicans on the Commission and the fact that her appointment isn’t up until 2023.
The problem that the SEC and Peirce are going to run into, and fairly soon, is that simply saying “there ought to be rules” isn’t adequate in the long run. This week, Pierce told Roll Call’s Sarah Wynn: “We’re trying to force those underlying bitcoin markets to look like our securities markets that we’re so familiar with and I just don’t see that as being a requirement under the Exchange Act or a product approval, so that’s the concern that I’ve raised.” OK, but assuming that an unregulated status quo for cryptocurrency isn’t viable, if it isn’t a security, then what is it? (Peirce did not respond to a FIN interview request.)
Peirce’s stances resemble a political party that’s always been in opposition and never had to govern. It is hard to find in Peirce’s many public utterances a vision of a system that would effectively regulate 21st century finance. In 2017, when she worked for George Mason University’s Mercatus Center, Peirce and two colleagues issued a response to a call for comment from the Office of the Comptroller of the Currency on bank charters for fintech startups, in which they wrote:
A regulatory framework for fintech companies should not focus on the survival of any individual company, but on keeping barriers to entry low and ensuring that firms have workable and effective plans in place to protect their customers in event of failure.
It’s an appealing juxtaposition, but it’s entirely unclear what framework Peirce and her colleagues were referring to here, nor what relationship the idea bears to actually existing fintech failures. The Wirecard fiasco might be an extreme example, but how exactly would regulators ensure customer protection without requiring the kind of registration and oversight that Peirce opposes?
In an ideal world, Gensler and his allies would work with Peirce to find some kind of regulatory compromise. And maybe the SEC is looking for some face-saving way to finally say yes to a Bitcoin-backed ETF. Most likely, though, the future is going to see a lot more Crypto Mom dissents.
This piece originally appeared in FIN, James Ledbetter’s fintech newsletter. Ledbetter is Chief Content Officer of Clarim Media, which owns Techonomy.